
What Is a Copay? How It Works and What You Pay
- Updated Date Nov 6, 2026
- Medical Billing
- Follow
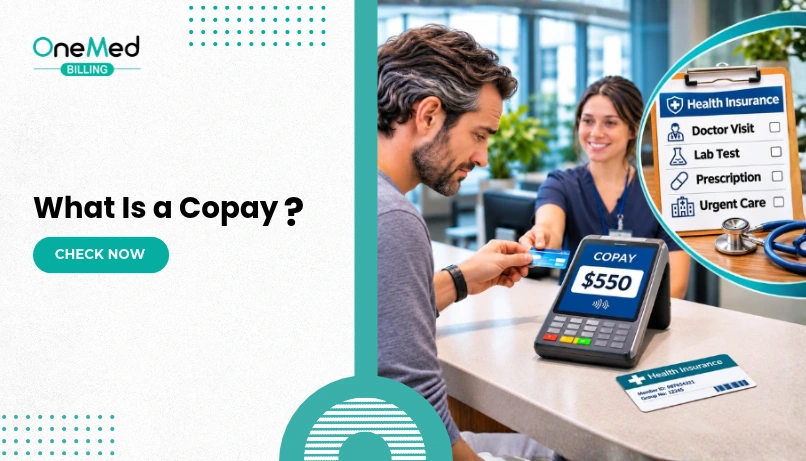
A copay, or copayment, is a fixed amount you pay for certain healthcare services covered by your health insurance plan. The amount can vary depending on the type of care you receive, such as a primary care visit, specialist appointment, urgent care visit, or prescription.
Copays are one of the most common out-of-pocket costs in health insurance and are part of your overall patient responsibility, along with deductibles and coinsurance.
In this guide, we explain how copays work, when you pay them, how they differ from other insurance costs, and where to find the copay amount for your plan.
How Does a Copay Work?
A copay works by splitting the cost of a covered healthcare service between you and your insurance plan.
Your insurance company sets a fixed copay amount for certain types of care. Providers can confirm these amounts through verification of benefits before the patient receives care.
For example, your plan might charge:
- $25 for a primary care visit
- $50 for a specialist visit
- $75 for urgent care
- $15 for a generic prescription
When you receive that service, you pay the copay amount required by your plan. The provider then bills your insurance for the rest of the covered service.
For example, suppose your primary care doctor charges $150 for a visit, but your insurance plan has a negotiated rate of $100 and your copay is $25.
You pay the $25 copay. Your insurance processes the remaining covered amount based on your plan rules.
The important point is that your copay usually stays the same for that type of service, even if the provider’s full charge is higher.
However, the way copays work can vary by plan. Some services may not have a copay at all, while others may require you to meet your deductible first. That is why it is always worth checking your plan details before a visit.
When Do You Pay a Copay?
You usually pay a copay when you receive a covered healthcare service.
For an office visit, the copay is often collected when you check in. For a prescription, you usually pay it when you pick up the medication at the pharmacy.
Common situations where a copay may apply include:
- Primary care visits
- Specialist appointments
- Urgent care visits
- Emergency room visits
- Prescription medications
The amount can be different for each type of service. For example, your plan may charge $25 for primary care, $50 for a specialist, and a different amount for urgent care.
Some services may not require a copay at all. Preventive care, for example, may be covered differently depending on your plan.
Whether you pay the copay before or after meeting your deductible also depends on the rules of your health insurance policy.
What Services Usually Have a Copay?
Copays commonly apply to services that you use regularly through your health plan. The exact amount depends on the type of care and your insurance policy.
Common examples include:
- Primary care visits - A routine visit with your family doctor or primary care physician may have a set copay.
- Specialist visits - Appointments with specialists such as cardiologists, dermatologists, or orthopedists often have a higher copay than primary care.
- Urgent care - Many plans charge a separate copay for urgent care visits.
- Emergency room visits - ER copays are often higher because emergency care is more expensive.
- Prescription medications - Your copay may depend on the drug tier, such as generic, preferred brand, or specialty medication.
Some services may have no copay at all. Certain preventive services, for example, may be covered without cost-sharing when you use an in-network provider and your plan rules are met.
Because copays vary by plan, it is best to check your insurance card, member portal, or Summary of Benefits and Coverage to see what you are expected to pay for each type of service.
Copay vs Deductible vs Coinsurance
The easiest way to understand the difference is:
- Copay = a fixed amount
- Deductible = an amount you pay first
- Coinsurance = a percentage you pay
Suppose your health plan has a $30 copay, a $2,000 deductible, and 20% coinsurance.
If you visit your primary care doctor and the visit has a $30 copay, you pay $30.
If you need a service that applies to your deductible, you may have to pay the covered cost yourself until you reach the $2,000 deductible.
After the deductible is met, your plan may start sharing the cost. If your coinsurance is 20% and the allowed cost of a service is $500, you would pay $100 and your insurance would pay the rest, according to your plan rules.
After a claim is processed, your Explanation of Benefits (EOB) can show how much was assigned to your copay, deductible, coinsurance, and other patient responsibility.
Does Paying a Copay Reduce Your Deductible?
Usually, no. Paying a copay does not reduce the amount of your deductible.
Your deductible is a separate amount you may need to pay for certain covered services before your insurance starts sharing more of the cost.
Copays are fixed amounts you pay for specific services, such as a doctor visit or prescription.
Because health plans can work differently, check your plan details to see whether any copays are applied toward your deductible.
Does Paying a Copay Reduce Your Yearly Out-of-Pocket Limit?
Usually, yes. Copays for covered in-network services generally count toward your yearly out-of-pocket maximum.
Your out-of-pocket maximum is the most you may have to pay during the year for covered in-network healthcare. Once you reach that limit, your insurance plan generally pays the full covered cost for the rest of the plan year.
Copays, deductibles, and coinsurance can all contribute toward this limit, depending on your plan.
How Can You Find Your Copay Amount?
To find your copay, check the details provided by your health insurance plan. Healthcare providers may also confirm copay and coverage information during the eligibility verification process.
You can also find it in:
- Your insurance ID card
- Your insurer’s member portal or mobile app
- Your Summary of Benefits and Coverage
- Your plan documents
If the amount is still unclear, you can call the customer service number on your insurance card and ask what copay applies to the service you need.
It is a good idea to check before the appointment, especially for specialist visits, urgent care, or prescriptions, because the copay can vary by service.
Frequently Asked Questions
Find quick answers to common questions about this topic, explained simply and clearly.
Do you have to pay a copay every time you visit the doctor?
Not always. You usually pay a copay only when your health plan assigns one to that type of visit or service. Some preventive visits or other covered services may have no copay.
Do you pay a copay before or after your deductible?
It depends on your health plan. Some services have a copay even before you meet your deductible, while others may require you to meet the deductible first.
Do preventive visits have a copay?
Many preventive services are covered without a copay when you use an in-network provider and meet your plan’s requirements. However, additional services provided during the same visit may still result in a separate cost.
Can you use an HSA or FSA to pay a copay?
Yes, in most cases. Copays are generally considered eligible medical expenses and can usually be paid with HSA or FSA funds.
How can I lower my copay?
You usually cannot change the copay set by your current health plan. However, you may be able to lower your overall costs by using in-network providers, choosing lower-cost prescription options, or selecting a plan with lower copays during enrollment. When comparing plans, also look at the premium, deductible, and coinsurance because a lower copay can sometimes come with higher costs elsewhere.